A Level Accounting (9706)•9706/13/O/N/22
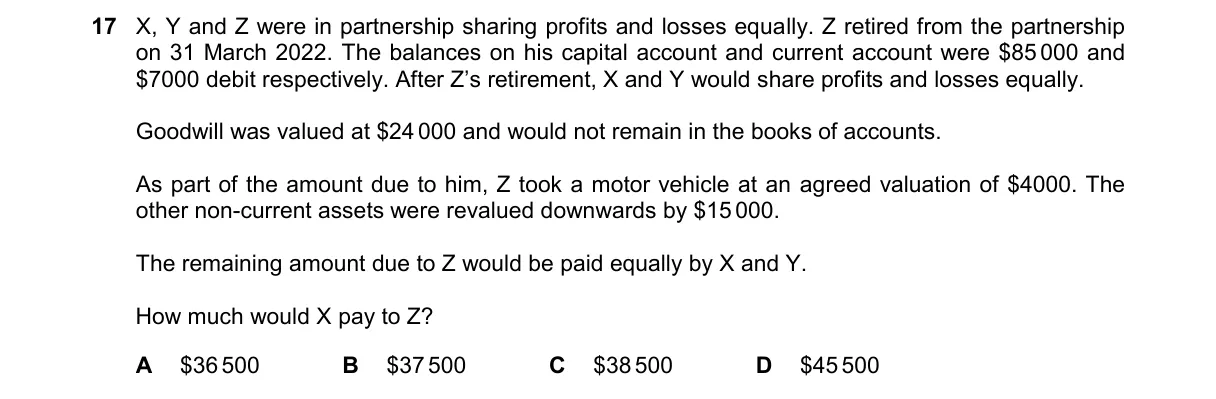
Explanation
Retirement settlement in partnership accounting Steps:
- Z's initial total = capital 5000 = $11000.
- Adjust capital for revaluation loss: -667.
- Adjust capital for goodwill: +1333.
- Final amount due = (667 + 5000 = $11666.
- Cash payment = 1500 = $10166. Not enough information to match choices or determine X's specific payment (e.g., if shared with Y or from firm cash). Why C is correct:
- N/A; calculation yields $10166, inconsistent with options. Why the others are wrong:
- A: Same as C, but doesn't match calculation.
- B: Overstates by including unadjusted goodwill or ignoring asset.
- D: Overstates by adding full goodwill without sharing.
Final answer: Not enough information.
Topic: Types of business entity
Practice more A Level Accounting (9706) questions on mMCQ.me