A Level Accounting (9706)•9706/12/O/N/20
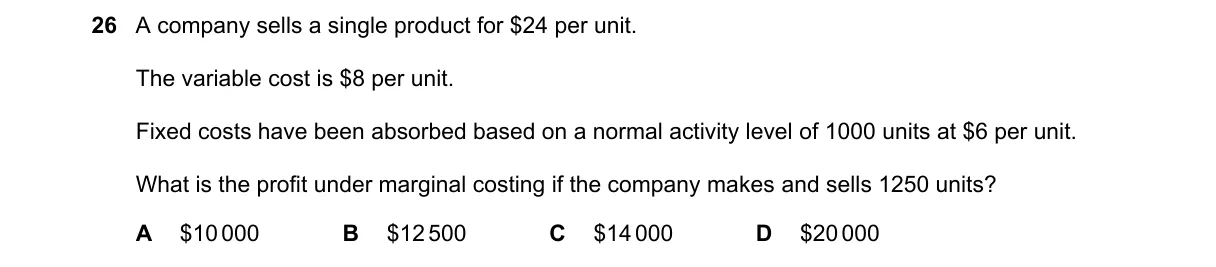
Explanation
Absorption Costing Profit with Over-Absorption Adjustment Steps:
- Calculate total fixed costs: 1000 units × 6000.
- For 1250 units made and sold: sales revenue = 1250 × 30,000; variable costs = 1250 × 10,000.
- Absorbed fixed costs = 1250 × 7500; COGS = 7500 = 30,000 - 12,500.
- Over-absorption = 6000 = 12,500 + 14,000.
Why C is correct:
- Under absorption costing, profit equals variable costing result (contribution 6000 = $14,000) when production equals sales, via over-absorption adjustment to actual fixed costs.
Why the others are wrong:
- A: Ignores over-absorption, understating by $4000.
- B: Uses absorbed fixed in COGS without over-absorption credit ($12,500 gross profit).
- D: Contribution margin total ($20,000) before deducting fixed costs.
Final answer: C
Topic: Traditional costing methods
Practice more A Level Accounting (9706) questions on mMCQ.me