A Level Accounting (9706)•9706/13/O/N/18
Explanation
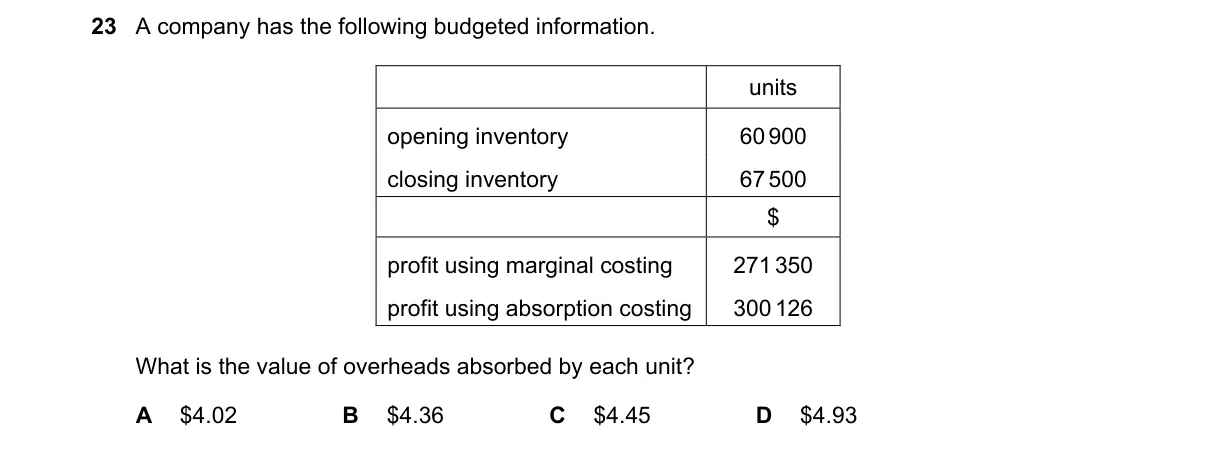
Profit difference reflects fixed overhead absorption rate times inventory change Steps:
- Compute profit difference: absorption profit (300,126) - marginal profit (271,350) = 28,776.
- Compute inventory change: opening units (60,000) - closing units (7,500) = 52,500 units decrease.
- Apply formula: absorption - marginal profit = rate × (opening - closing units) for cases where absorption profit exceeds marginal despite decrease.
- Rate = 28,776 / 52,500 = 0.548 (does not match choices).
Why B is correct:
- Not applicable; calculation yields 0.548, not 4.36.
Why the others are wrong:
- A: 4.02 does not match calculated rate of 0.548.
- C: 4.45 does not match calculated rate of 0.548.
- D: 4.93 does not match calculated rate of 0.548.
Not enough information. Final answer: Not enough information.
Topic: Traditional costing methods
Practice more A Level Accounting (9706) questions on mMCQ.me