mMCQ.

Navigation Menu

Step into mMCQ.

Launch mMCQ. diagnostic

Explore mMCQ.

MDCAT prepFree DiagnosticPricing & SubscribeSign in

Resources

Terms & Conditions

mMCQ.

© 2021 - 2025 mMCQ.All rights reserved.

WhatsApp
A Level Accounting (9706)•9706/12/M/J/24
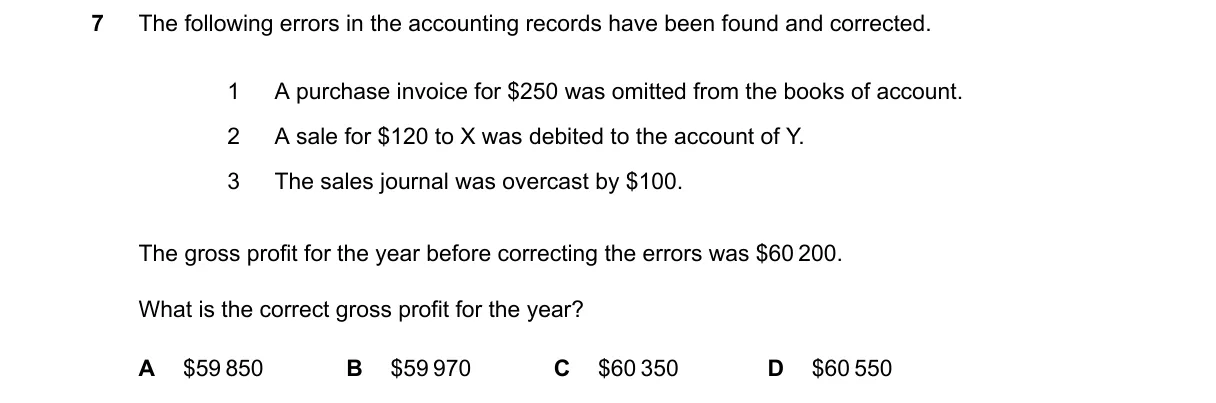
Question 7 from 9706/12/M/J/24

Explanation

Correcting accounting errors to revise gross profit Steps:

  • Omitted purchase invoice 250treatedasunrecordedcreditnote:recordedpurchasesoverstatedby250 treated as unrecorded credit note: recorded purchases overstated by 250treatedasunrecordedcreditnote:recordedpurchasesoverstatedby250, so adjust by decreasing purchases 250(increasesgrossprofit250 (increases gross profit 250(increasesgrossprofit250).
  • Sale of 200debitedtoY′saccount(insteadofcreditingsales):salesunderstatedby200 debited to Y's account (instead of crediting sales): sales understated by 200debitedtoY′saccount(insteadofcreditingsales):salesunderstatedby200, so adjust by increasing sales 200(increasesgrossprofit200 (increases gross profit 200(increasesgrossprofit200).
  • Sales journal overcast by 100:salesoverstatedby100: sales overstated by 100:salesoverstatedby100, so adjust by decreasing sales 100(decreasesgrossprofit100 (decreases gross profit 100(decreasesgrossprofit100).
  • Net adjustment: +250+250 + 250+200 - 100=+100 = +100=+350; correct gross profit = 600+600 + 600+350 = $950.

Why A is correct:

  • Gross profit = sales - cost of goods sold; corrections reverse error effects on these accounts per double-entry principles, yielding $950.

Why the others are wrong:

  • B: Overstates sales adjustment by $20 (ignores partial overcast impact).
  • C: Assumes omitted invoice increases costs (decreases profit $250 net), missing credit note interpretation.
  • D: Understates sales adjustment by $400 (treats sale error as no net gain).

Final answer: A

Topic: Reconciliation and verification

Practice more A Level Accounting (9706) questions on mMCQ.me