A Level Accounting (9706)•9706/12/M/J/24
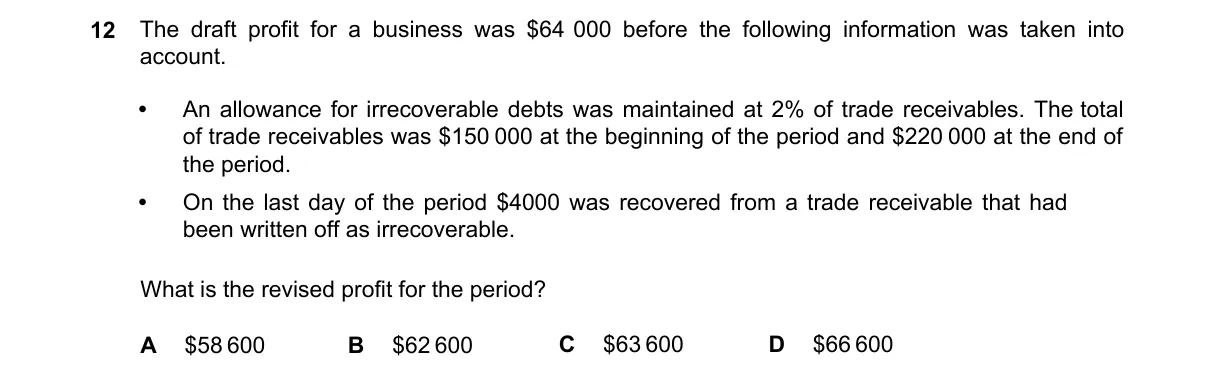
Explanation
Adjust profit for ending doubtful debts allowance and bad debt recovery
Steps:
- Compute ending allowance: 2% of 400 bad debt expense.
- Record recovery: $4,000 as income (previously written-off debt).
- Net adjustment to draft profit: -4,000 = +$3,600.
- Revised profit: 3,600 = $9,600.
Why D is correct:
- Bad debt expense equals the full ending allowance required (2% of ending receivables) under the percentage-of-receivables method, with recovery as separate income.
Why the others are wrong:
- A: Likely subtracts recovery from allowance without netting properly (400 + $2,000?).
- B: Treats recovery as expense or ignores it (200?).
- C: Uses change in allowance (6,000 - 2,400?).
Final answer: D
Topic: Preparation of financial statements
Practice more A Level Accounting (9706) questions on mMCQ.me