A Level Accounting (9706)•9706/13/M/J/21
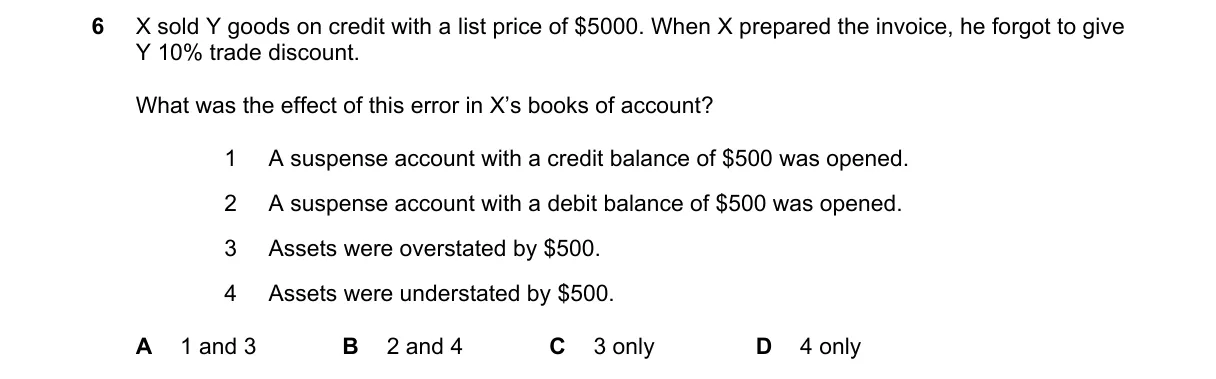
Explanation
Omission of trade discount understates recorded assets
Steps:
- Trade discount amount = 10% × 500.
- Correct invoice and recording = net $4500 for debtors and sales.
- Error: Forgot to give discount, so invoice and books show $4500 (discount applied by mistake).
- Result: Debtors (assets) recorded 5000.
Why C is correct:
- Assets understated by $500 because trade discount, per accounting standards, reduces the gross list price to net realizable value before recording; forgetting to "give" it implies unintended deduction, lowering book asset value below actual agreed receivable (definition from double-entry principle for sales on credit).
Why the others are wrong:
- A wrong: No suspense account opened, as initial sales entry balances without discrepancy.
- B wrong: Includes 2 (overstatement) and 4 (understatement duplicate), contradicting net effect of underrecording.
- D wrong: 4 duplicates 3 but implies isolated effect without confirming only assets impacted.
Final answer: C
Topic: The accounting system
Practice more A Level Accounting (9706) questions on mMCQ.me