A Level Accounting (9706)•9706/13/M/J/21
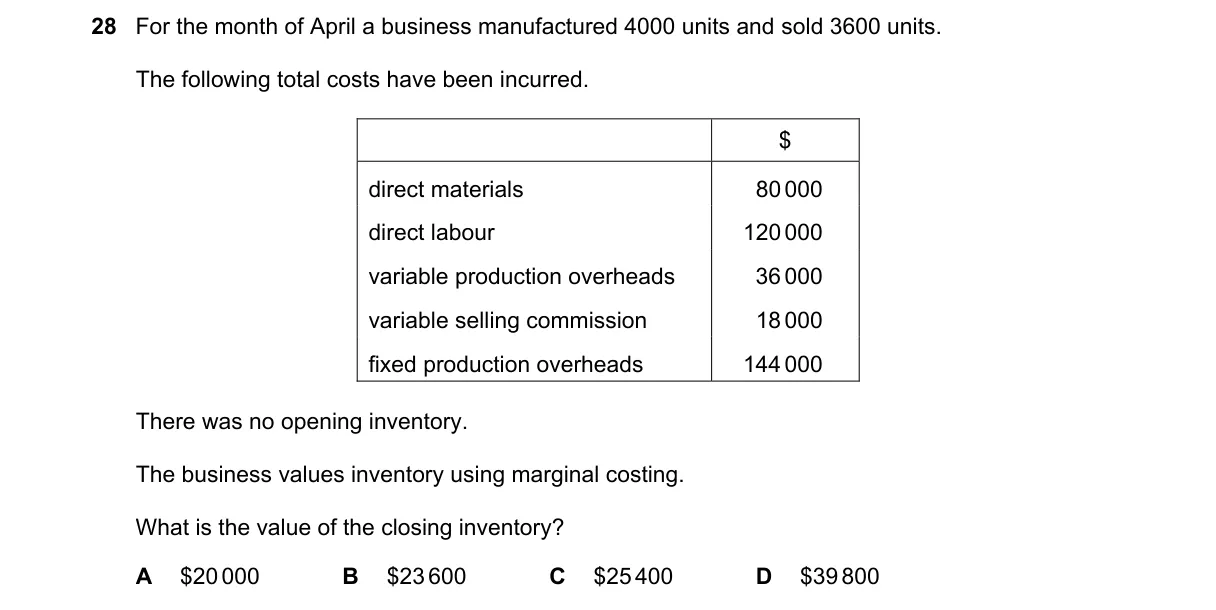
Explanation
Marginal costing values closing inventory at variable production costs only Steps:
- Total variable production costs = direct materials 120,000 + variable production overheads 236,000.
- Variable cost per unit = 59.
- Closing inventory units = 4,000 produced - 3,600 sold = 400 units.
- Closing inventory value = 400 units × 23,600. Why B is correct:
- Under marginal (variable) costing, inventory includes only variable manufacturing costs per unit multiplied by closing units (formula: closing units × variable cost/unit), equaling $23,600 (option B). Why the others are wrong:
- A: Excludes variable production overheads, using only direct costs (50/unit, $20,000 value).
- C: Applies absorption costing by adding fixed costs (e.g., 4.50/unit yields ~$25,000).
- D: Misapplies total costs including non-production fixed selling overheads or errs in unit calculation. Final answer: B
Topic: Traditional costing methods
Practice more A Level Accounting (9706) questions on mMCQ.me