A Level Accounting (9706)•9706/11/M/J/21
Explanation
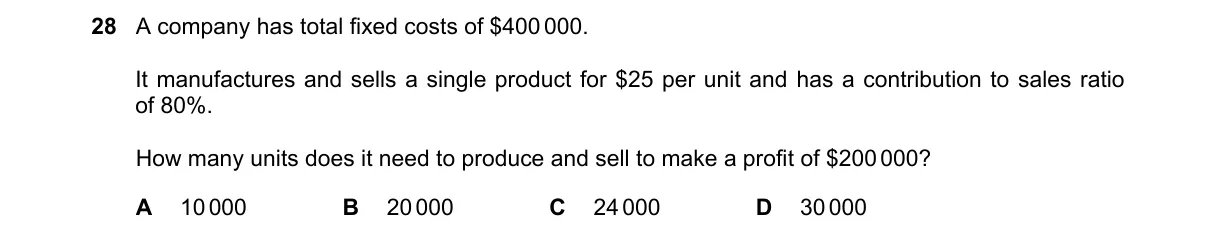
Target Profit in Units Using Contribution Margin
Steps:
- Contribution margin per unit = 20.
- Total contribution required = fixed costs + target profit = 200,000 = $600,000.
- Units to sell = total contribution required ÷ contribution margin per unit = 20 = 30,000.
- At 30,000 units, profit = (30,000 × 400,000 = $200,000.
Why D is correct:
- Formula for target profit units = (fixed costs + target profit) ÷ contribution margin per unit yields exactly 30,000.
Why the others are wrong:
- A: Yields contribution of 200,000 (loss).
- B: Yields contribution of 0 (break-even).
- C: Yields contribution of 80,000 (short of target).
Final answer: D
Topic: Costs and cost behaviour
Practice more A Level Accounting (9706) questions on mMCQ.me