A Level Accounting (9706)•9706/13/M/J/19
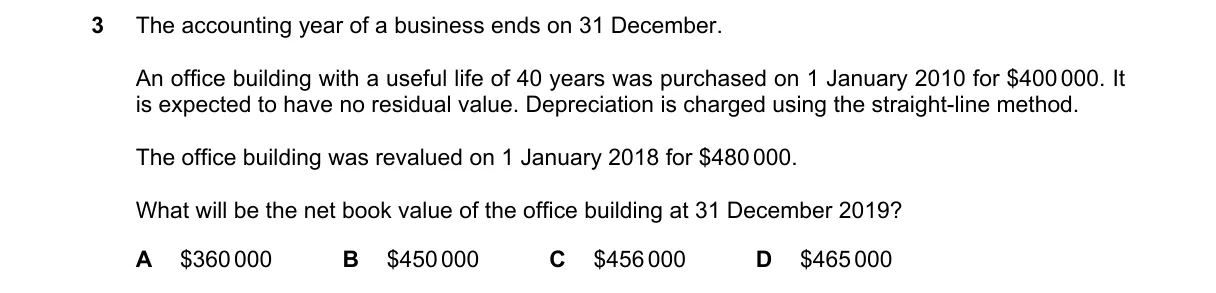
Explanation
Revaluation and Straight-Line Depreciation Over Remaining Life
Steps:
- NBV at 1 Jan 2018: 400,000 / 40 = 320,000.
- Revalue to 480,000.
- Remaining life: 40 - 8 = 32 years; annual depreciation = 15,000.
- Depreciation for 2018-2019 (2 years): 2 × 30,000.
- NBV at Dec 2019: 30,000 = $450,000.
Why B is correct:
- IAS 16 requires depreciating the revalued amount over remaining useful life, yielding $450,000 after 2 years.
Why the others are wrong:
- A: Uses original depreciation for 10 years ($300,000), ignoring revaluation.
- C: Applies no post-revaluation depreciation to $480,000.
- D: Likely miscalculates remaining life or annual rate (e.g., 40-year total instead of 32).
Final answer: B
Topic: Accounting for non-current assets
Practice more A Level Accounting (9706) questions on mMCQ.me