A Level Accounting (9706)•9706/13/M/J/19
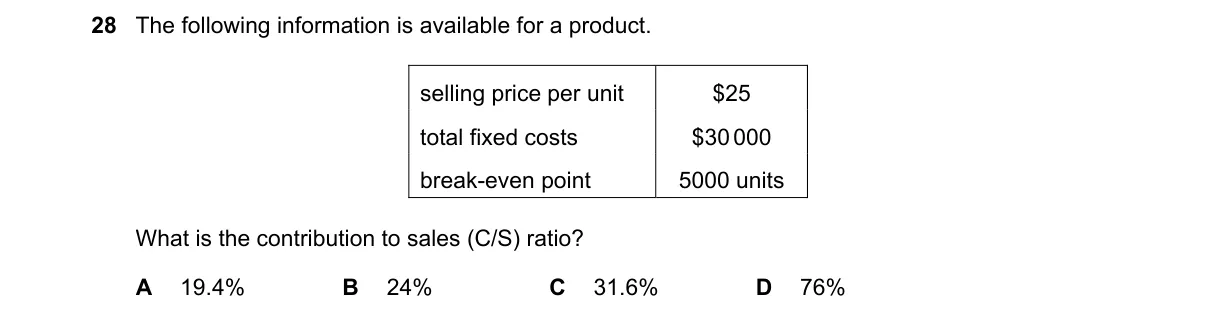
Explanation
Contribution to Sales Ratio via Break-Even Analysis
Steps:
- Compute contribution per unit using break-even formula: total fixed costs ÷ break-even units = 6 per unit.
- Determine CVS ratio: contribution per unit ÷ selling price per unit = 25 = 0.24 or 24%.
- Note: Given variable cost implies 6.
Why B is correct:
- CVS ratio is (contribution margin per unit / selling price), and break-even units = fixed costs / contribution per unit, so 6, then 25 = 24%.
Why the others are wrong:
- A. 19%: Underestimates contribution; ignores break-even override of variable cost data.
- C. 31%: Overstates ratio; possibly from erroneous fixed cost division.
- D. 76%: Inverts concept; resembles (1 - variable cost ratio) but misapplies data.
Final answer: B
Topic: Costs and cost behaviour
Practice more A Level Accounting (9706) questions on mMCQ.me