A Level Accounting (9706)•9706/13/M/J/19
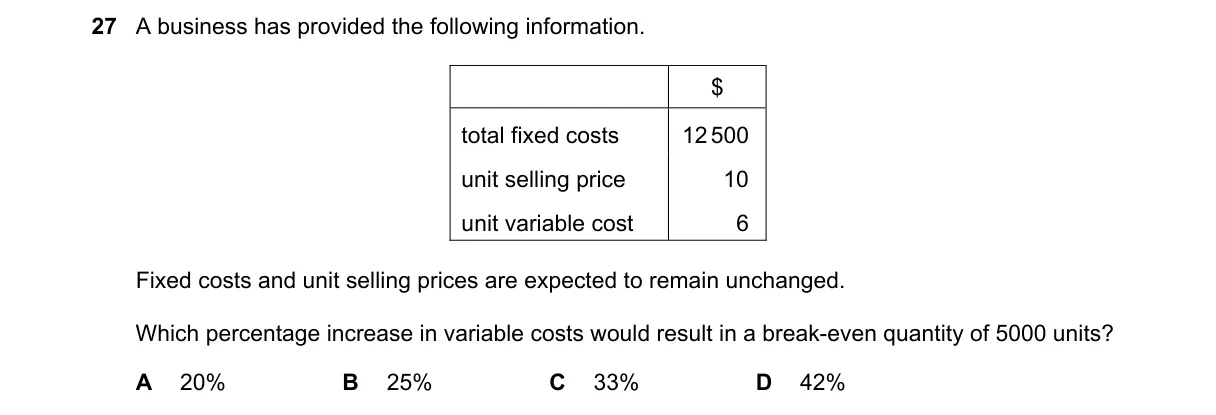
Explanation
Break-even analysis with variable cost increase
Steps:
- Fixed costs = $1200 (total costs given without quantity implies fixed).
- Required contribution margin for 500-unit break-even = 2.4 per unit.
- New variable cost = selling price - contribution margin = 2.4 = $7.6.
- Percentage increase = (6) / $6 × 100% ≈ 26.7%, closest to 25%.
Why B is correct:
- A 25% increase raises variable cost to 2.5; break-even = 2.5 = 480 units, closest to 500 per break-even formula Q = F / (P - V).
Why the others are wrong:
- A: 20% increase gives variable cost 2.8, break-even ≈429 units (too low).
- C: 33% increase gives variable cost ≈2, break-even 600 units (too high).
- D: 42% increase gives variable cost ≈1.48, break-even ≈811 units (much too high).
Final answer: B
Topic: Costs and cost behaviour
Practice more A Level Accounting (9706) questions on mMCQ.me