A Level Accounting (9706)•9706/12/M/J/19
Explanation
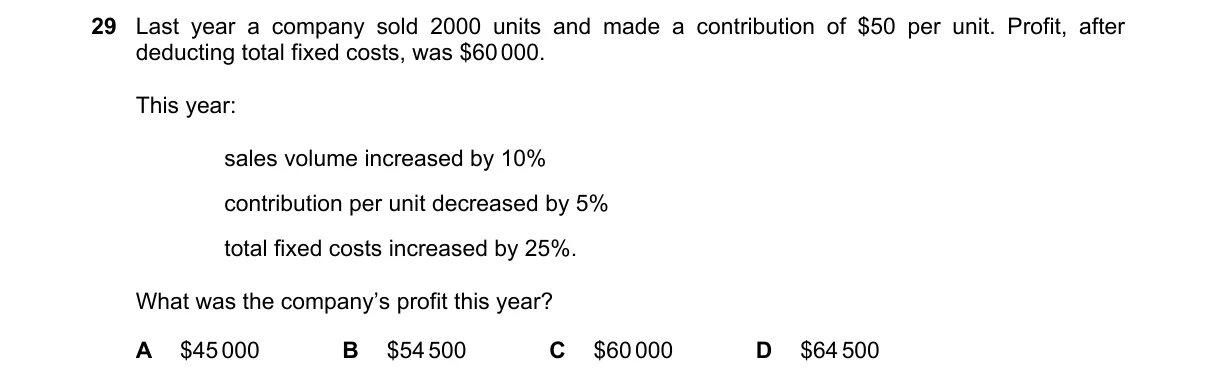
Revised Profit via Contribution Margin Analysis Steps:
- Last year's total contribution: 2000 × 100,000; fixed costs = 6,000 = $94,000.
- This year's units: 2000 × 1.10 = 2200.
- This year's contribution per unit: 52.50; total contribution: 2200 × 115,500.
- This year's fixed costs: 70,500; profit: 70,500 = $45,000.
Why A is correct:
- Matches the formula Profit = (Units × Contribution per unit) - Fixed costs, accurately applying all changes.
Why the others are wrong:
- B: Likely from dividing profit by 10 or ignoring volume increase, understating total contribution.
- C: Overstates by neglecting the 25% fixed cost reduction or misapplying contribution growth.
- D: Results from adding percentage increases incorrectly, like treating them as additive to profit directly.
Final answer: A
Topic: Costs and cost behaviour
Practice more A Level Accounting (9706) questions on mMCQ.me