A Level Accounting (9706)•9706/11/M/J/19
Explanation
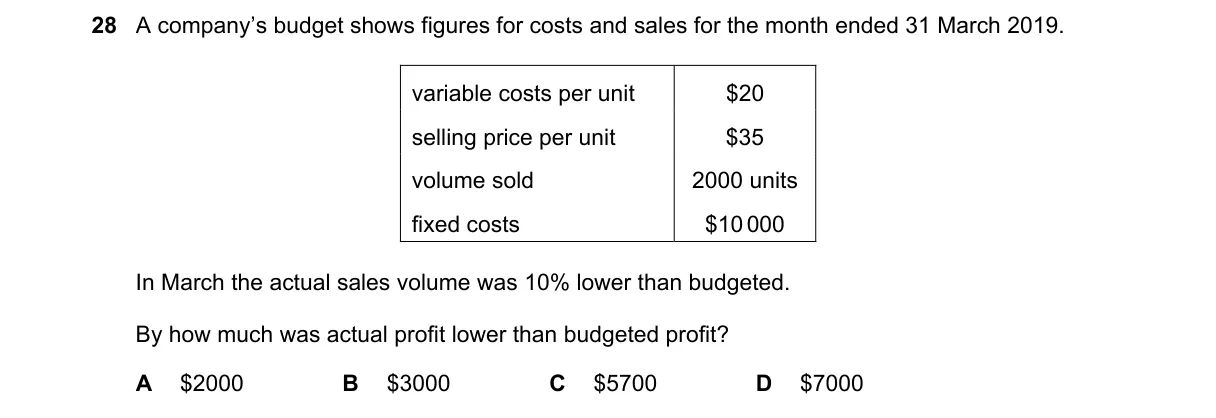
Sales volume variance determines profit difference Steps:
- Budgeted sales volume = 2000 units; actual = 2000 × 0.9 = 1800 units; shortfall = 200 units.
- Contribution margin per unit = 10 variable cost = $15.
- Lost contribution from shortfall = 200 units × 3000.
- Fixed costs remain $10,000 in both budgeted and actual, so profit differs by exactly the lost contribution.
Why B is correct:
- Sales volume variance formula: (budgeted volume - actual volume) × contribution margin per unit = profit shortfall of $3000.
Why the others are wrong:
- A: Calculates shortfall × fixed costs per unit (5, but doubled to $10 erroneously).
- C: Possibly actual revenue ($45,000) minus some misapplied total costs.
- D: Shortfall × inflated margin (e.g., 10), ignoring true contribution.
Final answer: B
Topic: Budgeting and budgetary control
Practice more A Level Accounting (9706) questions on mMCQ.me