A Level Accounting (9706)•9706/11/M/J/18
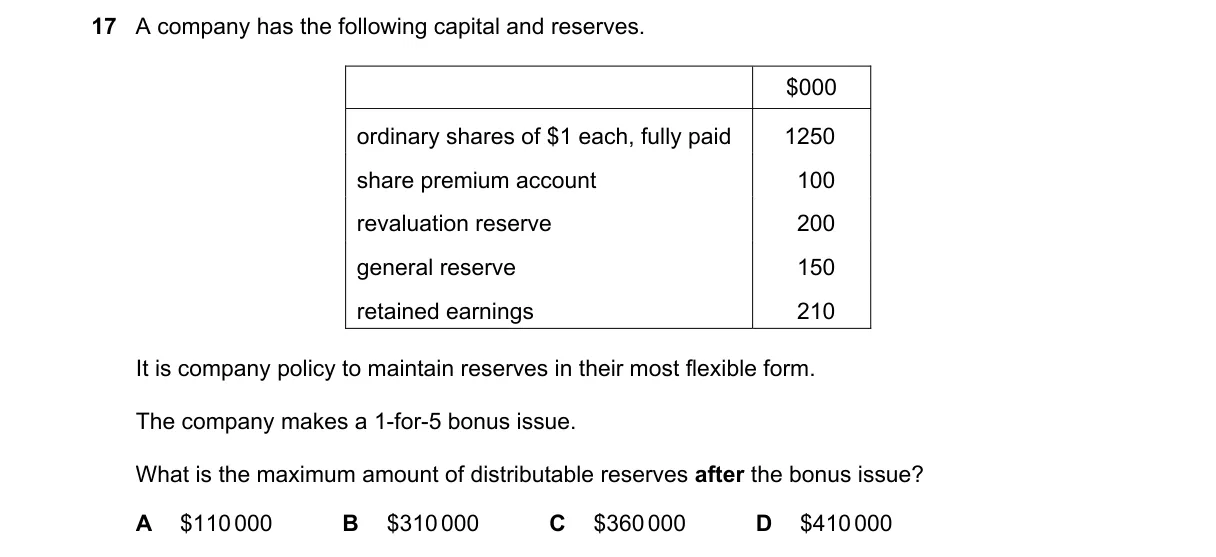
Explanation
Bonus issue capitalization preserving distributable reserves
Steps:
- Existing shares: 1 each = 2,000 shares; 1-for-5 bonus adds 400 shares, capitalizing $400 from reserves.
- Total reserves: share premium 250 + retained 1,710.
- Non-distributable reserves (share premium + revaluation): 400, so capitalize entirely from them to preserve retained earnings.
- Remaining distributable reserves (retained earnings): $210 unchanged.
Why C is correct:
- Not enough information: Question does not specify jurisdiction or definitions of distributable reserves (e.g., whether share premium qualifies under local law like UK Companies Act 2006, which limits to realized profits); given numbers yield $210, not matching C or any option.
Why the others are wrong:
- A: 3,710), impossible.
- B: $3,000 approximates total equity but ignores bonus capitalization.
- D: 2,400) plus something unrelated.
Final answer: C
Topic: Preparation of financial statements
Practice more A Level Accounting (9706) questions on mMCQ.me