O Level Accounting (7707)•7707/11/M/J/23
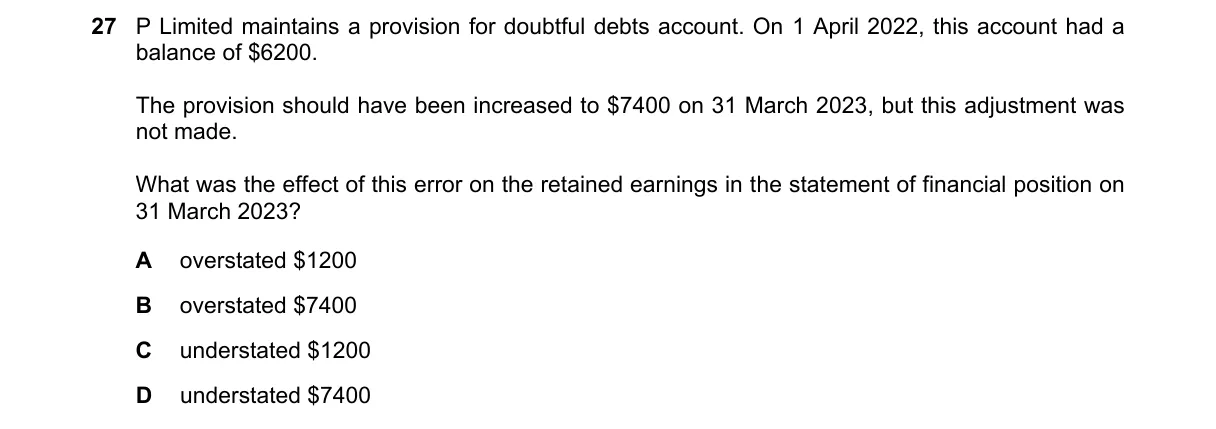
Explanation
Omitted provision adjustment overstates profit and retained earnings
Steps:
- Opening provision balance on 1 April 2022: $6,200 (credit).
- Required provision balance on 31 March 2023: $7,400 (credit).
- Required adjustment: increase provision by 6,200 = $1,200 (debit bad debt expense, credit provision).
- Adjustment not made: bad debt expense omitted, so profit for the year ending 31 March 2023 overstated by $1,200.
- Retained earnings (cumulative profits) thus overstated by $1,200 on 31 March 2023 statement of financial position.
Why B is correct:
- Under accrual accounting, increasing the provision records an expense that reduces net profit and retained earnings; omitting it overstates them by the adjustment amount ($1,200).
Why the others are wrong:
- A. 1,200).
- C. Error omits expense, causing overstatement, not understatement.
- D. $7,400 is the total required provision balance, irrelevant to retained earnings impact.
Final answer: B
Topic: Irrecoverable debts and provision for doubtful debts
Practice more O Level Accounting (7707) questions on mMCQ.me